
Most low ICV scores are not a business problem. They are a classification problem — local spend recorded in a way the formula cannot read. Before restructuring your supply chain, it is worth checking whether your accounts are simply failing to evidence what you already do.
Start by finding where score is lost
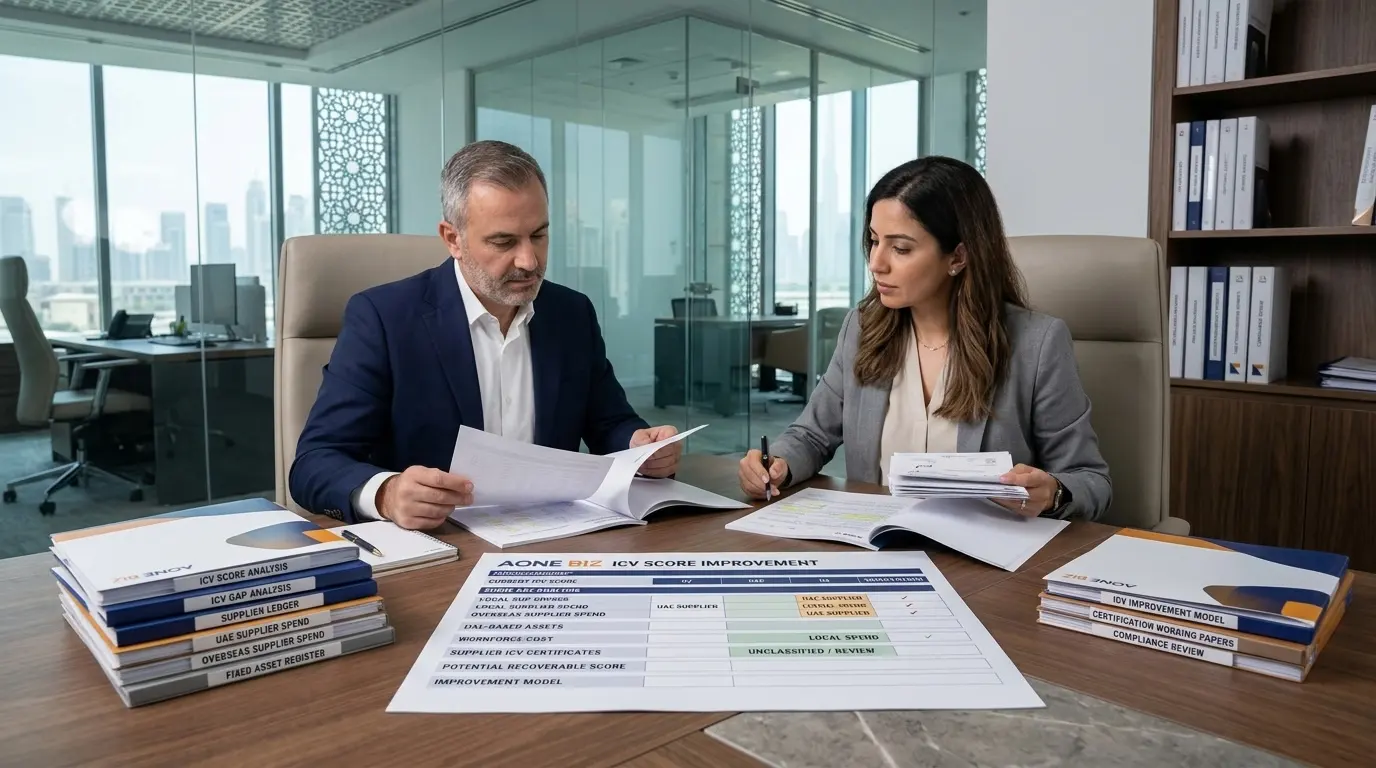
The formula reads defined categories from audited accounts. Score is lost in two ways: spend that genuinely goes overseas, and UAE spend that the accounts do not attribute to a scoring category.
The second is far more common and far cheaper to fix. A gap analysis compares what you actually spend locally against what your accounts can evidence — and the difference is usually recoverable score.
Classification fixes: the quick wins
- Separate UAE from overseas supplier spend in the chart of accounts, not in a spreadsheet afterwards
- Split payroll between Emirati and expatriate employees, since Emirati cost is weighted more favourably
- Identify UAE-based assets distinctly in the fixed asset register
- Track locally manufactured goods separately from imported ones
- Collect supplier ICV certificates — a supplier’s own certificate can improve your score on spend with them
That last point is routinely ignored and routinely valuable. Asking your significant UAE suppliers for their certificates costs nothing and can lift your score measurably.
These changes cost nothing at setup and are laborious to retrofit. Building them into monthly bookkeeping means the analysis produces itself.
Structural ICV score improvement
Where classification is already right and the score is still low, the levers are genuine business decisions rather than accounting ones.
Shift spend to UAE suppliers where cost and quality permit, particularly to suppliers who themselves hold ICV certificates. Invest in UAE-based assets rather than leasing from overseas. Increase Emirati employment, which carries weighting in the formula and separately addresses Emiratisation obligations for qualifying employers. Manufacture or assemble locally where the economics work — goods made in the UAE score strongly.
These take time to affect the score, because it is calculated from a completed financial year. A decision made now shows in the certificate issued after next year’s audit.
Why timing matters more than effort
Your score reflects a completed financial year. Improvements made in month eleven barely register; the same changes made in month one affect the whole period.
So the useful sequence is: certify, understand the gaps, implement changes early in the following year, then certify again on a full year of improved data. Businesses that try to improve a score in the weeks before a tender are working on a year that has already closed.
Model before you certify
Once the audit is signed, the inputs are fixed. Reviewing classification before certification is the last point at which score can still be recovered without changing the business.
We run that review as part of the audit where possible, because the same team seeing the trial balance can identify misclassified local spend while there is still time to reclassify it correctly.
Realistic expectations
An importer with an overseas supply chain, no UAE assets and a small expatriate team will not score highly, and no amount of reclassification changes that. The formula is measuring something real.
What reclassification does is ensure you score what you have actually earned. That gap is frequently significant, and it is the honest place to start — before anyone proposes restructuring a supply chain to chase a percentage.
Frequently asked questions
Most often classification. Local spend recorded under generic overhead headings cannot be attributed to the categories that score.
Classification fixes affect the next certification. Structural changes take a full financial year to show, because the score is calculated from completed accounts.
Yes, and collecting them is one of the cheapest improvements available. A supplier's certificate can lift your score on spend with them.
Yes - Emirati workforce cost is weighted favourably, and it also addresses Emiratisation obligations for qualifying employers.
No. Once the audit is complete the inputs are fixed. Review classification before certification, not after.
Only if the tender value justifies it. Start with classification - most businesses recover meaningful score without changing anything operationally.
Getting started
Send us your current certificate and your trial balance. We will show you how much score is being lost to classification alone — which is usually the number that changes the conversation.